Insights
I've got valuable information and resources to share. Explore away! And check back often.
 Read Post
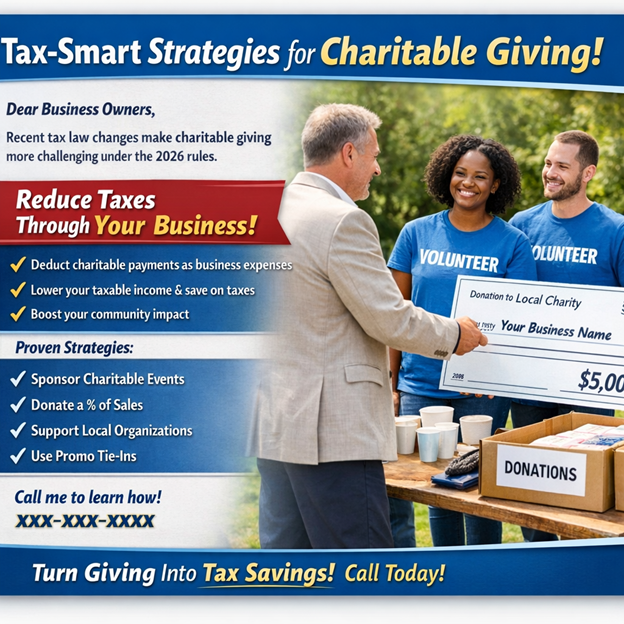
Business owners: you're likely overpaying taxes on money you already give away. You’re giving to charity…but getting little to no tax benefit in return. I’m seeing this more and more in 2026. Because of recent tax changes, a lot of personal giving: • Doesn’t move the needle on taxes • Is done with fully taxed dollars Here’s what most people miss: There may be a more efficient way to structure that same giving. Which can mean: • Lower taxable income • Reduced self-employment exposure • Better overall tax positioning Not because of a loophole…but because of how it’s structured. Examples I’m reviewing with clients right now: • Event sponsorships that double as marketing • Revenue-based giving strategies • Community partnerships that drive visibility Same dollars. Different structure. Different outcome. If you’re already giving or planning to this year, this is worth getting right. If you want to see if this could apply to your situation, feel free to message me and we can walk through it. Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional. Disclosures: thrivent.com/social
Business owners: you're likely overpaying taxes on money you already give away. You’re giving to charity…but getting little to no tax benefit in return. I’m seeing this more and more in 2026. Because of recent tax changes, a lot of personal giving: • Doesn’t move the needle on taxes • Is done with fully taxed dollars Here’s what most people miss: There may be a more efficient way to structure that same giving. Which can mean: • Lower taxable income • Reduced self-employment exposure • Better overall tax positioning Not because of a loophole…but because of how it’s structured. Examples I’m reviewing with clients right now: • Event sponsorships that double as marketing • Revenue-based giving strategies • Community partnerships that drive visibility Same dollars. Different structure. Different outcome. If you’re already giving or planning to this year, this is worth getting right. If you want to see if this could apply to your situation, feel free to message me and we can walk through it. Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional. Disclosures: thrivent.com/social
Read Post
Here’s a tax change most business owners haven’t noticed yet... Starting in 2026, many employer-paid meals, coffee, and breakroom snacks are no longer deductible. You can still offer them. But you don’t get the tax break anymore. Not a huge cost on its own, but over time it adds up and can influence decisions around employee perks, culture, and office experience. This is a good reminder that sometimes the biggest financial impacts come from the smallest line items. If you want to discuss, please call me on my direct line at 360-777-6911 or email me at joe.davis@thrivent.com. Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional. Disclosures: thrivent.com/social
Here’s a tax change most business owners haven’t noticed yet... Starting in 2026, many employer-paid meals, coffee, and breakroom snacks are no longer deductible. You can still offer them. But you don’t get the tax break anymore. Not a huge cost on its own, but over time it adds up and can influence decisions around employee perks, culture, and office experience. This is a good reminder that sometimes the biggest financial impacts come from the smallest line items. If you want to discuss, please call me on my direct line at 360-777-6911 or email me at joe.davis@thrivent.com. Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional. Disclosures: thrivent.com/social
Read Post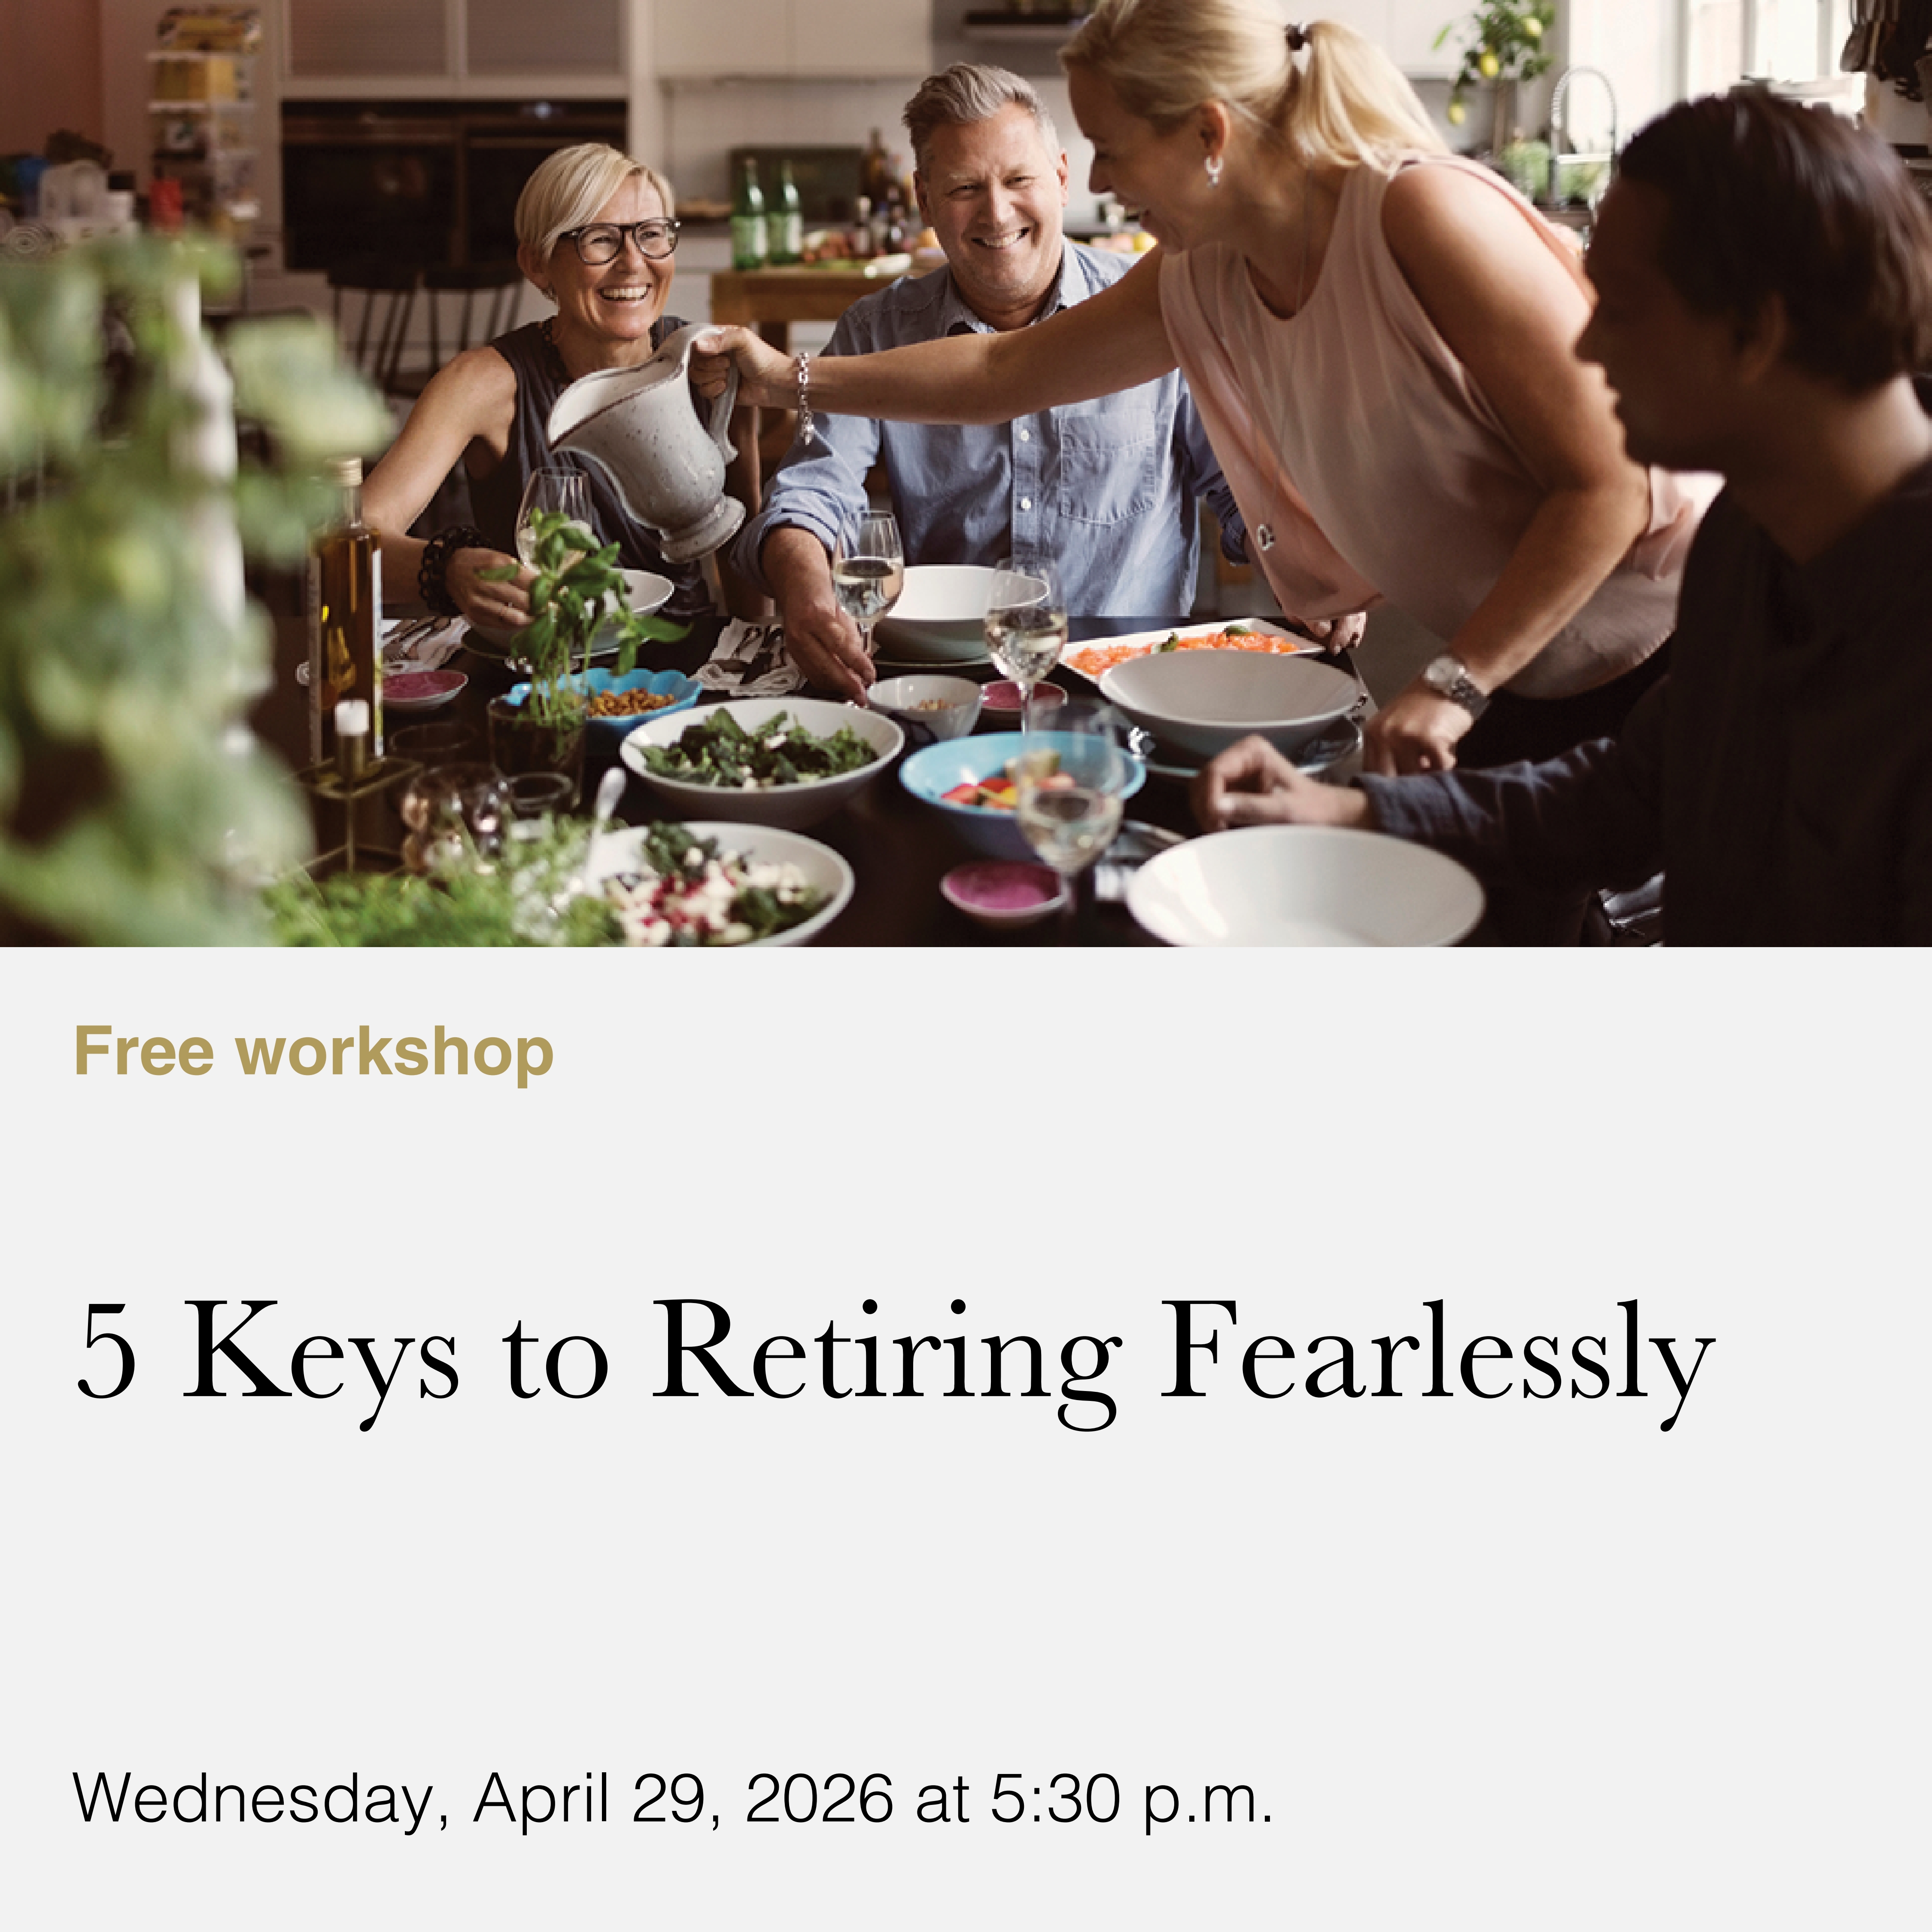
Gig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy program titled “5 Keys to Retiring Fearlessly” workshop and discover practical strategies to secure your financial future. Build guaranteed income? Protect your savings from market volatility? Safeguard your retirement from life’s “what ifs?” Workshop is 530pm-630pm at the Gig Harbor Library main conference room on 29 April and refreshments will be available. Find out more about Joe Davis at https://connect.thrivent.com › joe-davis. No products will be sold. 27878-8M R9-25
Gig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy program titled “5 Keys to Retiring Fearlessly” workshop and discover practical strategies to secure your financial future. Build guaranteed income? Protect your savings from market volatility? Safeguard your retirement from life’s “what ifs?” Workshop is 530pm-630pm at the Gig Harbor Library main conference room on 29 April and refreshments will be available. Find out more about Joe Davis at https://connect.thrivent.com › joe-davis. No products will be sold. 27878-8M R9-25
Read Post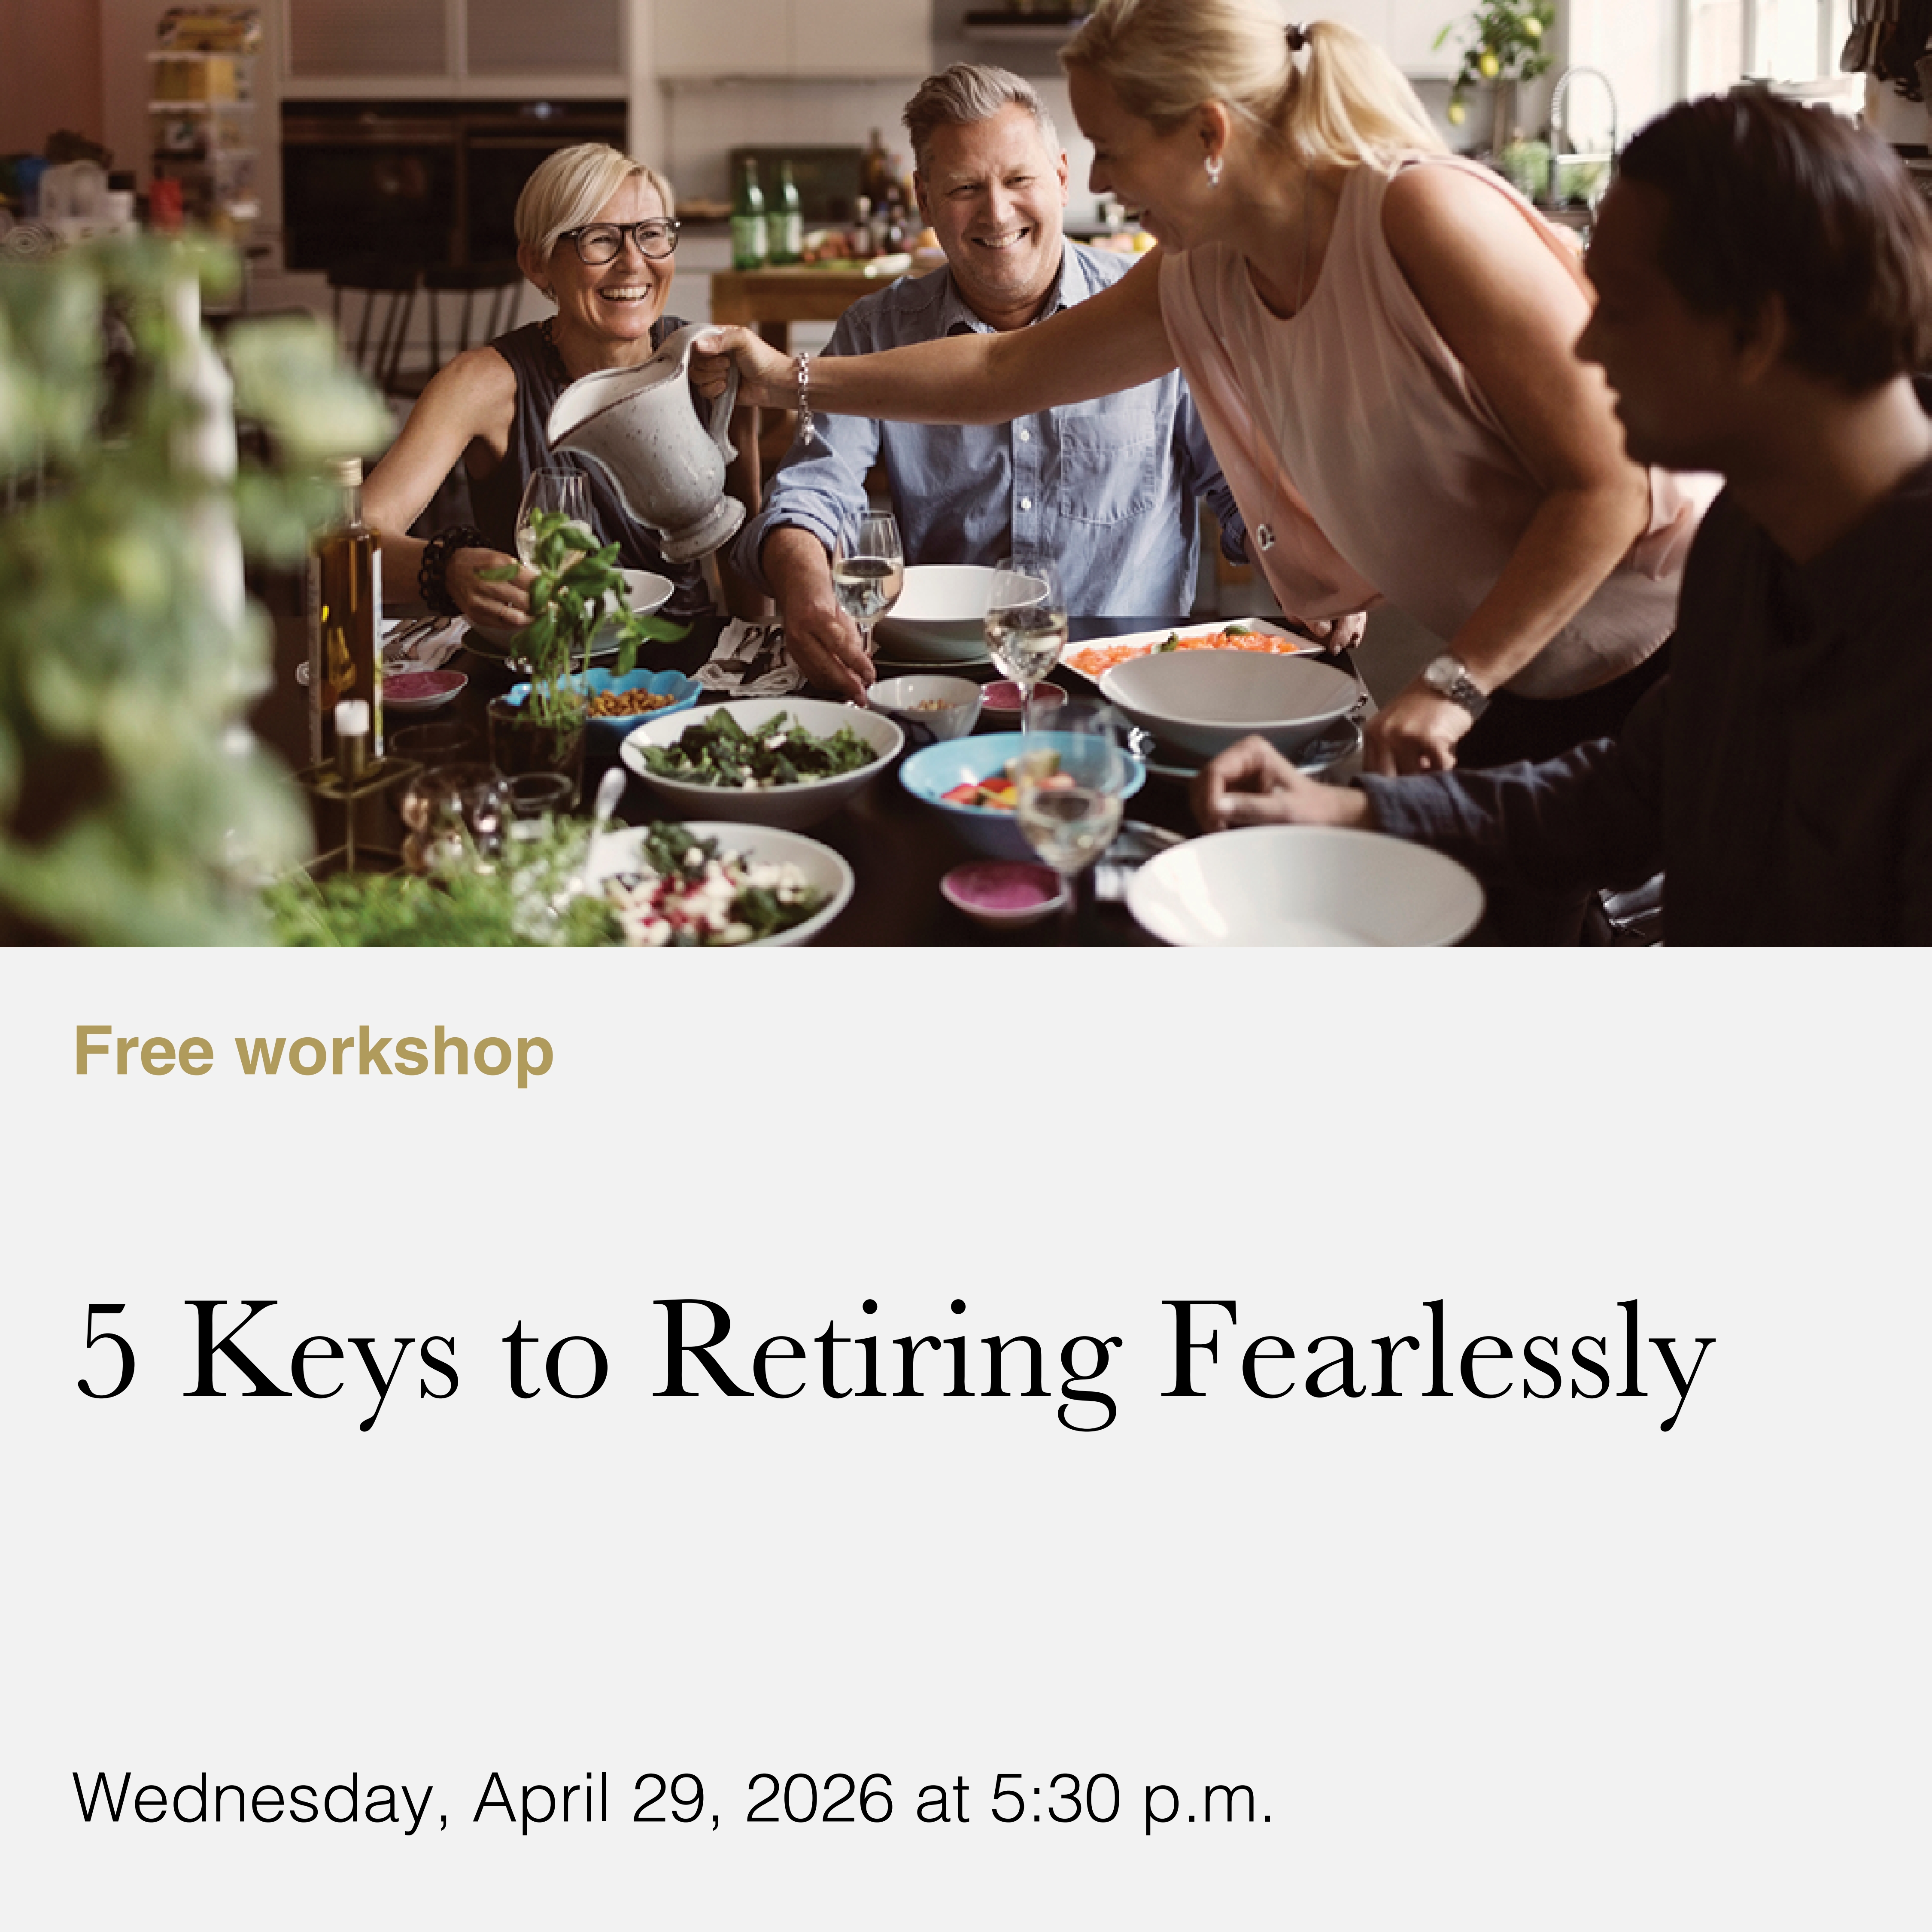
Gig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy Program titled Five Keys to Retiring Fearless on 29 April from 5:30PM-6:30PM. https://calendar.piercecountylibrary.org/event/15866258 Wondering if you’ll have enough for retirement? Get answers and expert guidance at our upcoming “5 Keys to Retiring Fearlessly” workshop. Learn how to create reliable income, protect your savings, and plan for the unexpected. Don’t miss out—sign up now and start planning for a fearless future! https://connect.thrivent.com/joe-davis RSVP here or contact Joe Davis at 360-777-6911 or joe.davis@thrivent.com. There will be light refreshments! No products will be sold. 27878-8M R9-25
Gig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy Program titled Five Keys to Retiring Fearless on 29 April from 5:30PM-6:30PM. https://calendar.piercecountylibrary.org/event/15866258 Wondering if you’ll have enough for retirement? Get answers and expert guidance at our upcoming “5 Keys to Retiring Fearlessly” workshop. Learn how to create reliable income, protect your savings, and plan for the unexpected. Don’t miss out—sign up now and start planning for a fearless future! https://connect.thrivent.com/joe-davis RSVP here or contact Joe Davis at 360-777-6911 or joe.davis@thrivent.com. There will be light refreshments! No products will be sold. 27878-8M R9-25
Read PostGig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy Program titled Five Keys to Retiring Fearless on 29 April from 5:30PM-6:30PM. https://calendar.piercecountylibrary.org/event/15866258 Wondering if you'll have enough saved for your retirement? Join this dynamic workshop packed with strategies to help secure your financial future. Learn how you can retire with confidence by addressing your biggest financial concerns and sharing practical strategies for a secure future. • Build guaranteed income and protect your savings from market volatility. • Optimize your retirement plan for tax efficiency and long-term growth. • Safeguard your finances and loved ones from life’s “what ifs.” RSVP here or contact Joe Davis at 360-777-6911 or joe.davis@thrivent.com. There will be light refreshments! No products will be sold. 27878-8M R9-25
Gig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy Program titled Five Keys to Retiring Fearless on 29 April from 5:30PM-6:30PM. https://calendar.piercecountylibrary.org/event/15866258 Wondering if you'll have enough saved for your retirement? Join this dynamic workshop packed with strategies to help secure your financial future. Learn how you can retire with confidence by addressing your biggest financial concerns and sharing practical strategies for a secure future. • Build guaranteed income and protect your savings from market volatility. • Optimize your retirement plan for tax efficiency and long-term growth. • Safeguard your finances and loved ones from life’s “what ifs.” RSVP here or contact Joe Davis at 360-777-6911 or joe.davis@thrivent.com. There will be light refreshments! No products will be sold. 27878-8M R9-25
Read Post
Late Filing Costs Estate $1.5M—Will Yours Be Next? The Tax Cuts and Jobs Act established a very favorable federal estate and gift tax regime, and the One Big Beautiful Bill Act made it permanent. For 2026, the unified federal estate and gift tax exemption is a whopping $15 million, or effectively $30 million for a married couple because each spouse is entitled to a separate exemption. For 2027 and beyond, the unified exemption amount will be adjusted for inflation. The portion of your taxable estate that exceeds the federal exemption is subject to federal estate tax at graduated rates up to a top rate of 40 percent. You reach the 40 percent rate quickly, once the value of your estate exceeds the exemption by more than $1 million. With today’s generous exemption, you may have concluded that you have no federal estate tax worries. It’s possible, in fact, that the whole subject of the federal estate tax may have fallen off your radar. Not so fast! If you’re married, you need to keep one important thing front of mind to optimize your federal estate and gift tax position: the so-called portable exemption privilege. If you want to discuss, please call me directly at 360-777-6911 or email joe.davis@thrivent.com. disclosures:thrivent.com/social Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Late Filing Costs Estate $1.5M—Will Yours Be Next? The Tax Cuts and Jobs Act established a very favorable federal estate and gift tax regime, and the One Big Beautiful Bill Act made it permanent. For 2026, the unified federal estate and gift tax exemption is a whopping $15 million, or effectively $30 million for a married couple because each spouse is entitled to a separate exemption. For 2027 and beyond, the unified exemption amount will be adjusted for inflation. The portion of your taxable estate that exceeds the federal exemption is subject to federal estate tax at graduated rates up to a top rate of 40 percent. You reach the 40 percent rate quickly, once the value of your estate exceeds the exemption by more than $1 million. With today’s generous exemption, you may have concluded that you have no federal estate tax worries. It’s possible, in fact, that the whole subject of the federal estate tax may have fallen off your radar. Not so fast! If you’re married, you need to keep one important thing front of mind to optimize your federal estate and gift tax position: the so-called portable exemption privilege. If you want to discuss, please call me directly at 360-777-6911 or email joe.davis@thrivent.com. disclosures:thrivent.com/social Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Read Post
If your donating clothes or household goods to charity, there's an IRS trap you need to know about! In a recent Tax Court case, a taxpayer lost a $6,760 charitable deduction—not because the donations were improper, but because his documentation failed to meet strict technical requirements. The court didn’t question his generosity. It denied the deduction because the receipts and Form 8283 were incomplete. Here’s the key issue: For non-cash donations over $250, you must obtain a contemporaneous written acknowledgment from the charity. For donations over $500, you must also maintain detailed records showing what you donated, when you acquired the items, and their cost or basis. Form 8283 must be completed accurately, including donation dates and fair market values. Generic receipts that say “miscellaneous household items” are not enough. And once an audit begins, you cannot fix missing documentation afterward. The deduction is simply lost. The safest approach is proactive. Before donating, prepare a detailed list of items, including descriptions and estimated values; take photographs; and provide the list to the charity so it can reference the list in its acknowledgment. Keep all supporting records with your tax files. The bottom line: Good intentions are not sufficient. With charitable deductions, documentation is everything. If you want to discuss donations of clothing and household goods, please call me directly at 360-777-6911 or email joe.davis@thrivent.com. disclosures:thrivent.com/social Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
If your donating clothes or household goods to charity, there's an IRS trap you need to know about! In a recent Tax Court case, a taxpayer lost a $6,760 charitable deduction—not because the donations were improper, but because his documentation failed to meet strict technical requirements. The court didn’t question his generosity. It denied the deduction because the receipts and Form 8283 were incomplete. Here’s the key issue: For non-cash donations over $250, you must obtain a contemporaneous written acknowledgment from the charity. For donations over $500, you must also maintain detailed records showing what you donated, when you acquired the items, and their cost or basis. Form 8283 must be completed accurately, including donation dates and fair market values. Generic receipts that say “miscellaneous household items” are not enough. And once an audit begins, you cannot fix missing documentation afterward. The deduction is simply lost. The safest approach is proactive. Before donating, prepare a detailed list of items, including descriptions and estimated values; take photographs; and provide the list to the charity so it can reference the list in its acknowledgment. Keep all supporting records with your tax files. The bottom line: Good intentions are not sufficient. With charitable deductions, documentation is everything. If you want to discuss donations of clothing and household goods, please call me directly at 360-777-6911 or email joe.davis@thrivent.com. disclosures:thrivent.com/social Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Read Post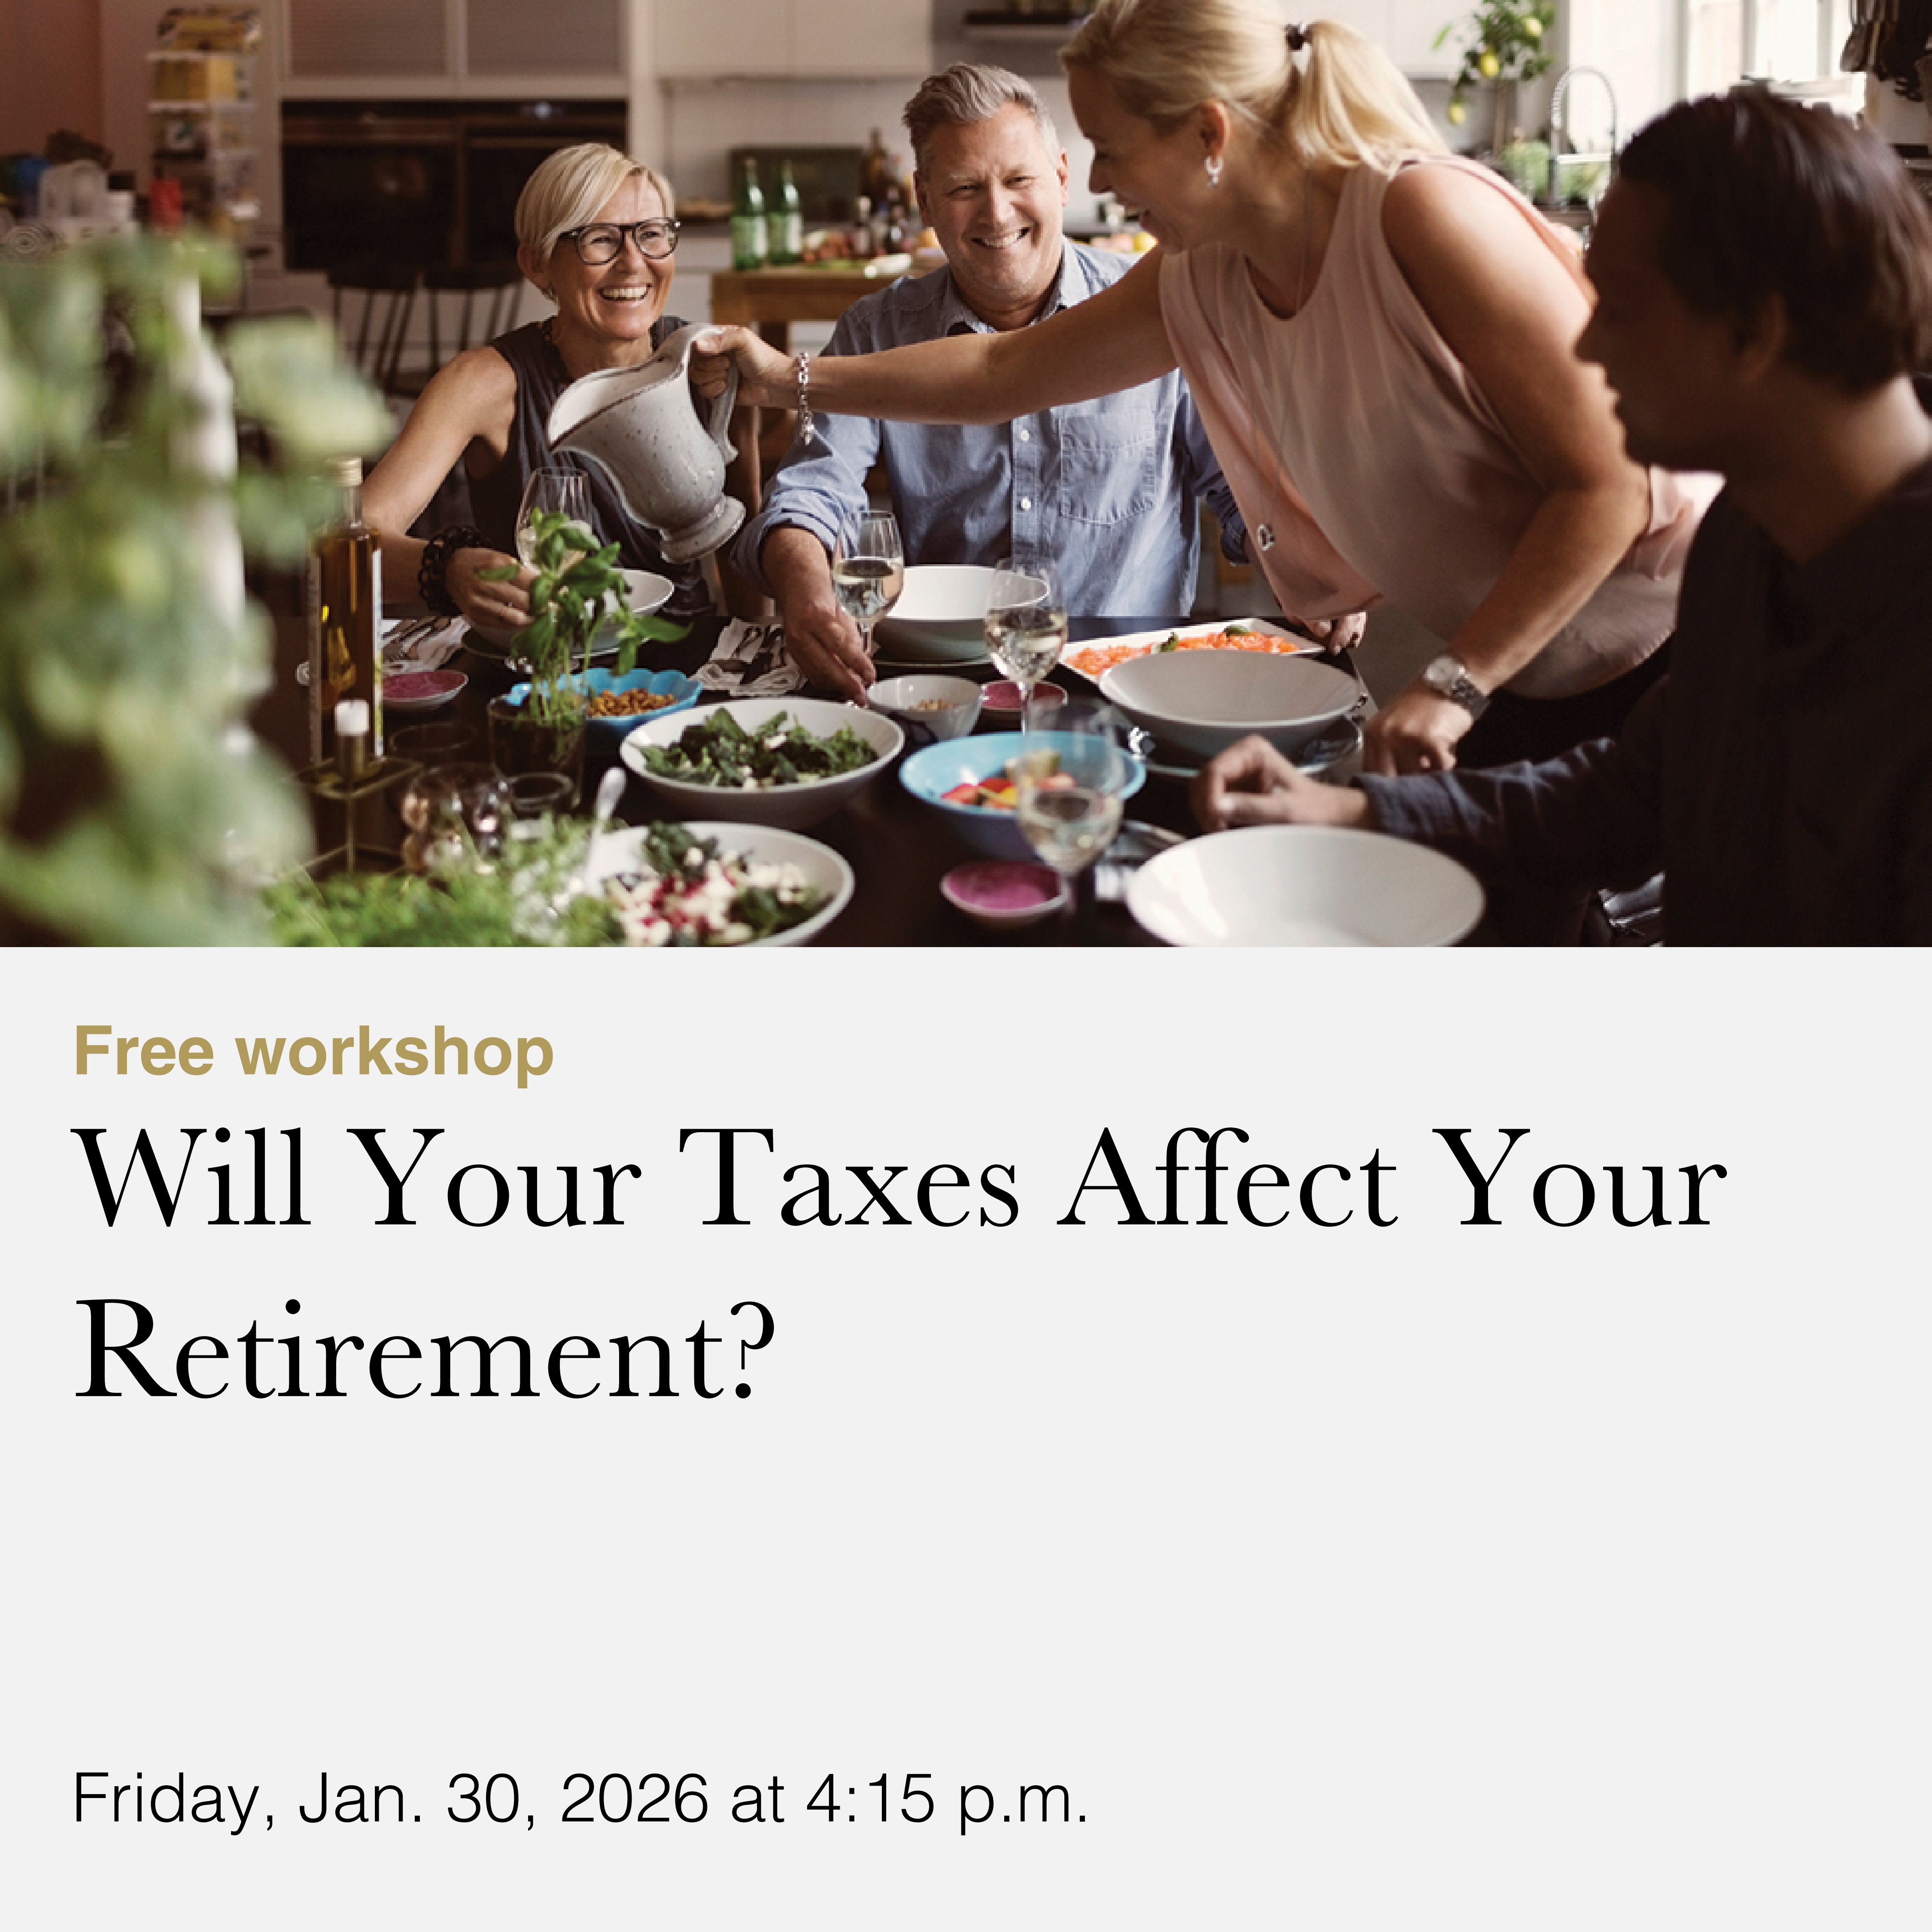
When you retire, you leave behind many things—the daily grind, the commute to work, and maybe even your previous home. However, one thing that will always remain is your tax bill. When you understand how investments are taxed and set strategies accordingly, you can make the right decisions that help keep income taxes in check. Will Your Taxes Affect Your Retirement? Join me for this event on Friday 6 March at 5pm at the Gig Harbor Library at 4424 Point Fosdick Dr, Gig Harbor, WA 98335, where you will learn strategies to work toward a lower tax bracket in retirement! There will be light refreshments. No products will be sold. Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration. Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional. See thrivent.com/social for important disclosures. 27878-15M R11-20
When you retire, you leave behind many things—the daily grind, the commute to work, and maybe even your previous home. However, one thing that will always remain is your tax bill. When you understand how investments are taxed and set strategies accordingly, you can make the right decisions that help keep income taxes in check. Will Your Taxes Affect Your Retirement? Join me for this event on Friday 6 March at 5pm at the Gig Harbor Library at 4424 Point Fosdick Dr, Gig Harbor, WA 98335, where you will learn strategies to work toward a lower tax bracket in retirement! There will be light refreshments. No products will be sold. Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration. Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional. See thrivent.com/social for important disclosures. 27878-15M R11-20

 Read Post
Exciting news! Thrivent has been named to Fortune’s World’s Most Admired Companies list for the first time. Honored to be part of an organization recognized for its innovation, quality of management, financial soundness and commitment to long-term value. Learn more about this recognition here: https://bit.ly/466lt23
Exciting news! Thrivent has been named to Fortune’s World’s Most Admired Companies list for the first time. Honored to be part of an organization recognized for its innovation, quality of management, financial soundness and commitment to long-term value. Learn more about this recognition here: https://bit.ly/466lt23